What is PVS’s Economic Moat?
What are the barriers to entry when it comes to offshore wind installation?
1. The “Monopoly” Factor – Only PVS Can Do It, Others Find It Nearly Impossible to Replicate?
There are 3 reasons why other enterprises find it almost impossible to compete with PVS for market share in Vietnam:
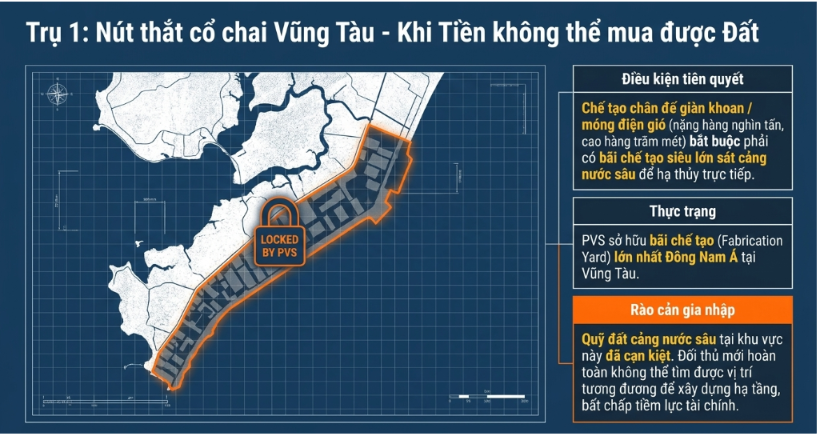
Deep-water Port and Fabrication Yard Assets: To manufacture offshore drilling jacket foundations or wind turbine foundations (weighing thousands of tons, reaching hundreds of meters tall), enterprises must have a massive fabrication yard adjacent to a deep-water port for direct launching. PVS currently owns Southeast Asia’s largest port and fabrication yard system in Vung Tau. The deep-water port assets there are already fully utilized; new enterprises, despite having capital, cannot find equivalent locations to build comparable infrastructure.
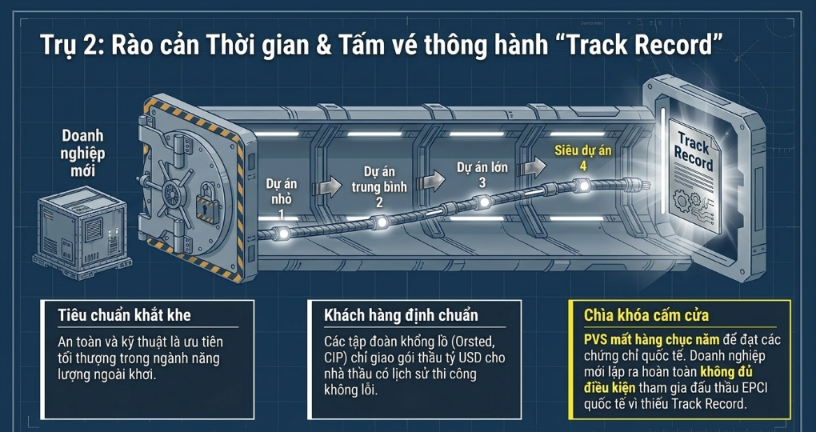
“License to Operate” from Global Supply Chain Track Record: In the offshore energy sector, safety and technical standards are paramount. Clients (such as Orsted, CIP) only award multi-billion-dollar contracts to contractors with a “flawless construction history” (Track Record). PVS has spent decades acquiring international certifications and completing mega-projects. A newly established enterprise will lack this Track Record and therefore will not qualify for international EPCI tender participation.
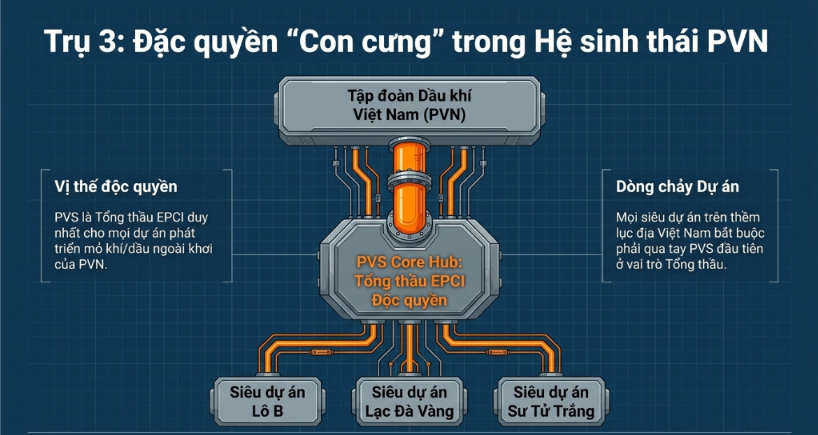
Privileged Position as “Favored Child” in the PVN Ecosystem: PVS is the exclusive EPCI general contractor for all offshore oil and gas field development projects of Vietnam National Oil & Gas Corporation (PVN). Any mega-project on Vietnam’s continental shelf (Block B, Lac Da Vang, White Lion) will be handled by PVS first in its capacity as General Contractor.
2. Who Are PVS’s Competitors?
PVS’s competitive landscape is divided into two very distinct arenas:
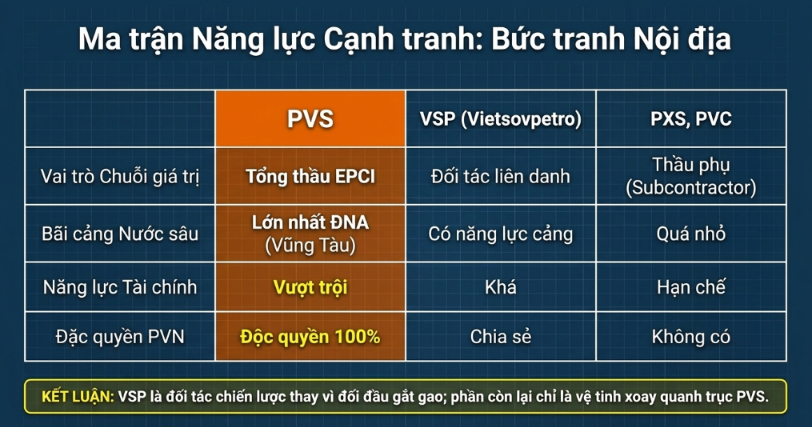
A. Domestic Market: Virtually “One Horse, One Rider” Within Vietnam, PVS faces no significant rival in the offshore EPCI general contracting sector.
Vietnam-Russia Joint Venture Vietsovpetro (VSP): VSP possesses installation and port capabilities, but in practice, VSP frequently forms joint ventures with PVS itself to pursue contracts (such as wind energy projects) rather than engaging in direct head-to-head competition.
Other steel structure companies (such as PXS, PVC): Their financial capacity and fabrication yard scale are too small. They typically serve only as subcontractors, receiving secondary work packages (pipe processing, welding) from PVS as the prime contractor, lacking the strength to bid as general contractors.
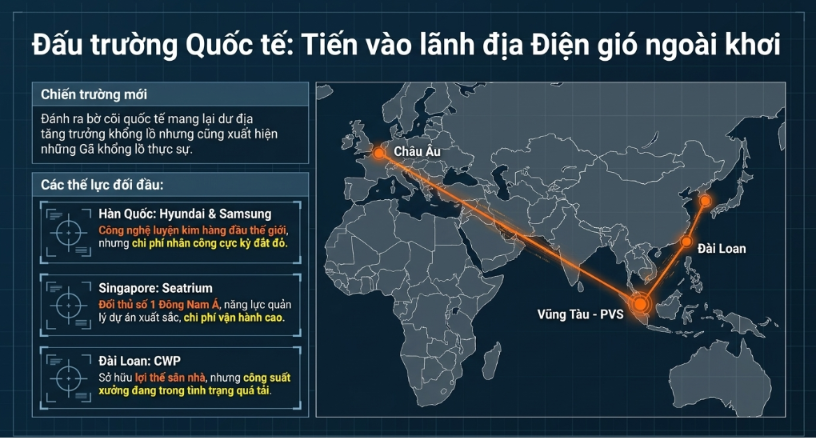
B. International Market (Offshore Wind Sector): Competing with “Giants” When PVS expands internationally (Taiwan, Europe) to win offshore wind contracts, true competitors emerge. These are leading global heavy industrial conglomerates:
South Korea: Hyundai Heavy Industries, Samsung Heavy Industries. They possess world-leading metallurgy and manufacturing technology, but their major weakness is extremely high labor costs.
Singapore: Seatrium (the legal entity following the merger of Sembcorp Marine and Keppel O&M). This is PVS’s largest competitor in Southeast Asia with excellent project management capabilities.
Taiwan: Century Wind Power (CWP) – a domestic Taiwan competitor with home market advantage but operating at over-capacity in its facilities.
PVS’s Critical Advantage Over International Competitors: While not as technologically superior as South Korea or Singapore in core capabilities, PVS wins contracts through cost competitiveness advantages (inexpensive Vietnamese labor, excellent welding skills) and the ability to source domestic steel (from HPG) that is steadily improving, making PVS’s profit margins more attractive to international project developers.
Understanding this economic moat will greatly reinforce confidence in fundamental analysis (FA). Smart Money accumulating PVS shares at current sideways price levels is precisely because they recognize this dominant position cannot be undermined for at least the next 5-10 years.
This entire article presents a comprehensive perspective. If you are interested in how PVS has grown recently, check here!
Wishing all investors good health and success!
E: luongtuyen.271298@gmail.com
Best regards,
Luong Dang Bich Tuyen (Ms)
M: (84) 78 480 9235
Disclaimer: All information and opinions in this article are for reference purposes only and represent the personal views of the author, and are not investment advice or recommendations. Readers should independently assess risks and take full responsibility for their own trading decisions.

